Choosing A Group Benefits Provider

brandableContent

What to Look for in a Group Benefits Provider (and How We Help Employers Get It Right)

If you’re reviewing your group benefits plan—or starting one for the first time—you’ve likely realized how overwhelming it can be to compare providers. At our firm, we work with employers across Canada to help them make informed, confident decisions about their benefits programs. And if there’s one thing we’ve learned, it’s this: the lowest quote doesn’t always mean the best value.

As independent group benefits specialists, our job is to guide you through the process, simplify your options, and build a plan that fits your business and your team.

Here are five key things we help employers evaluate when choosing a group benefits provider:

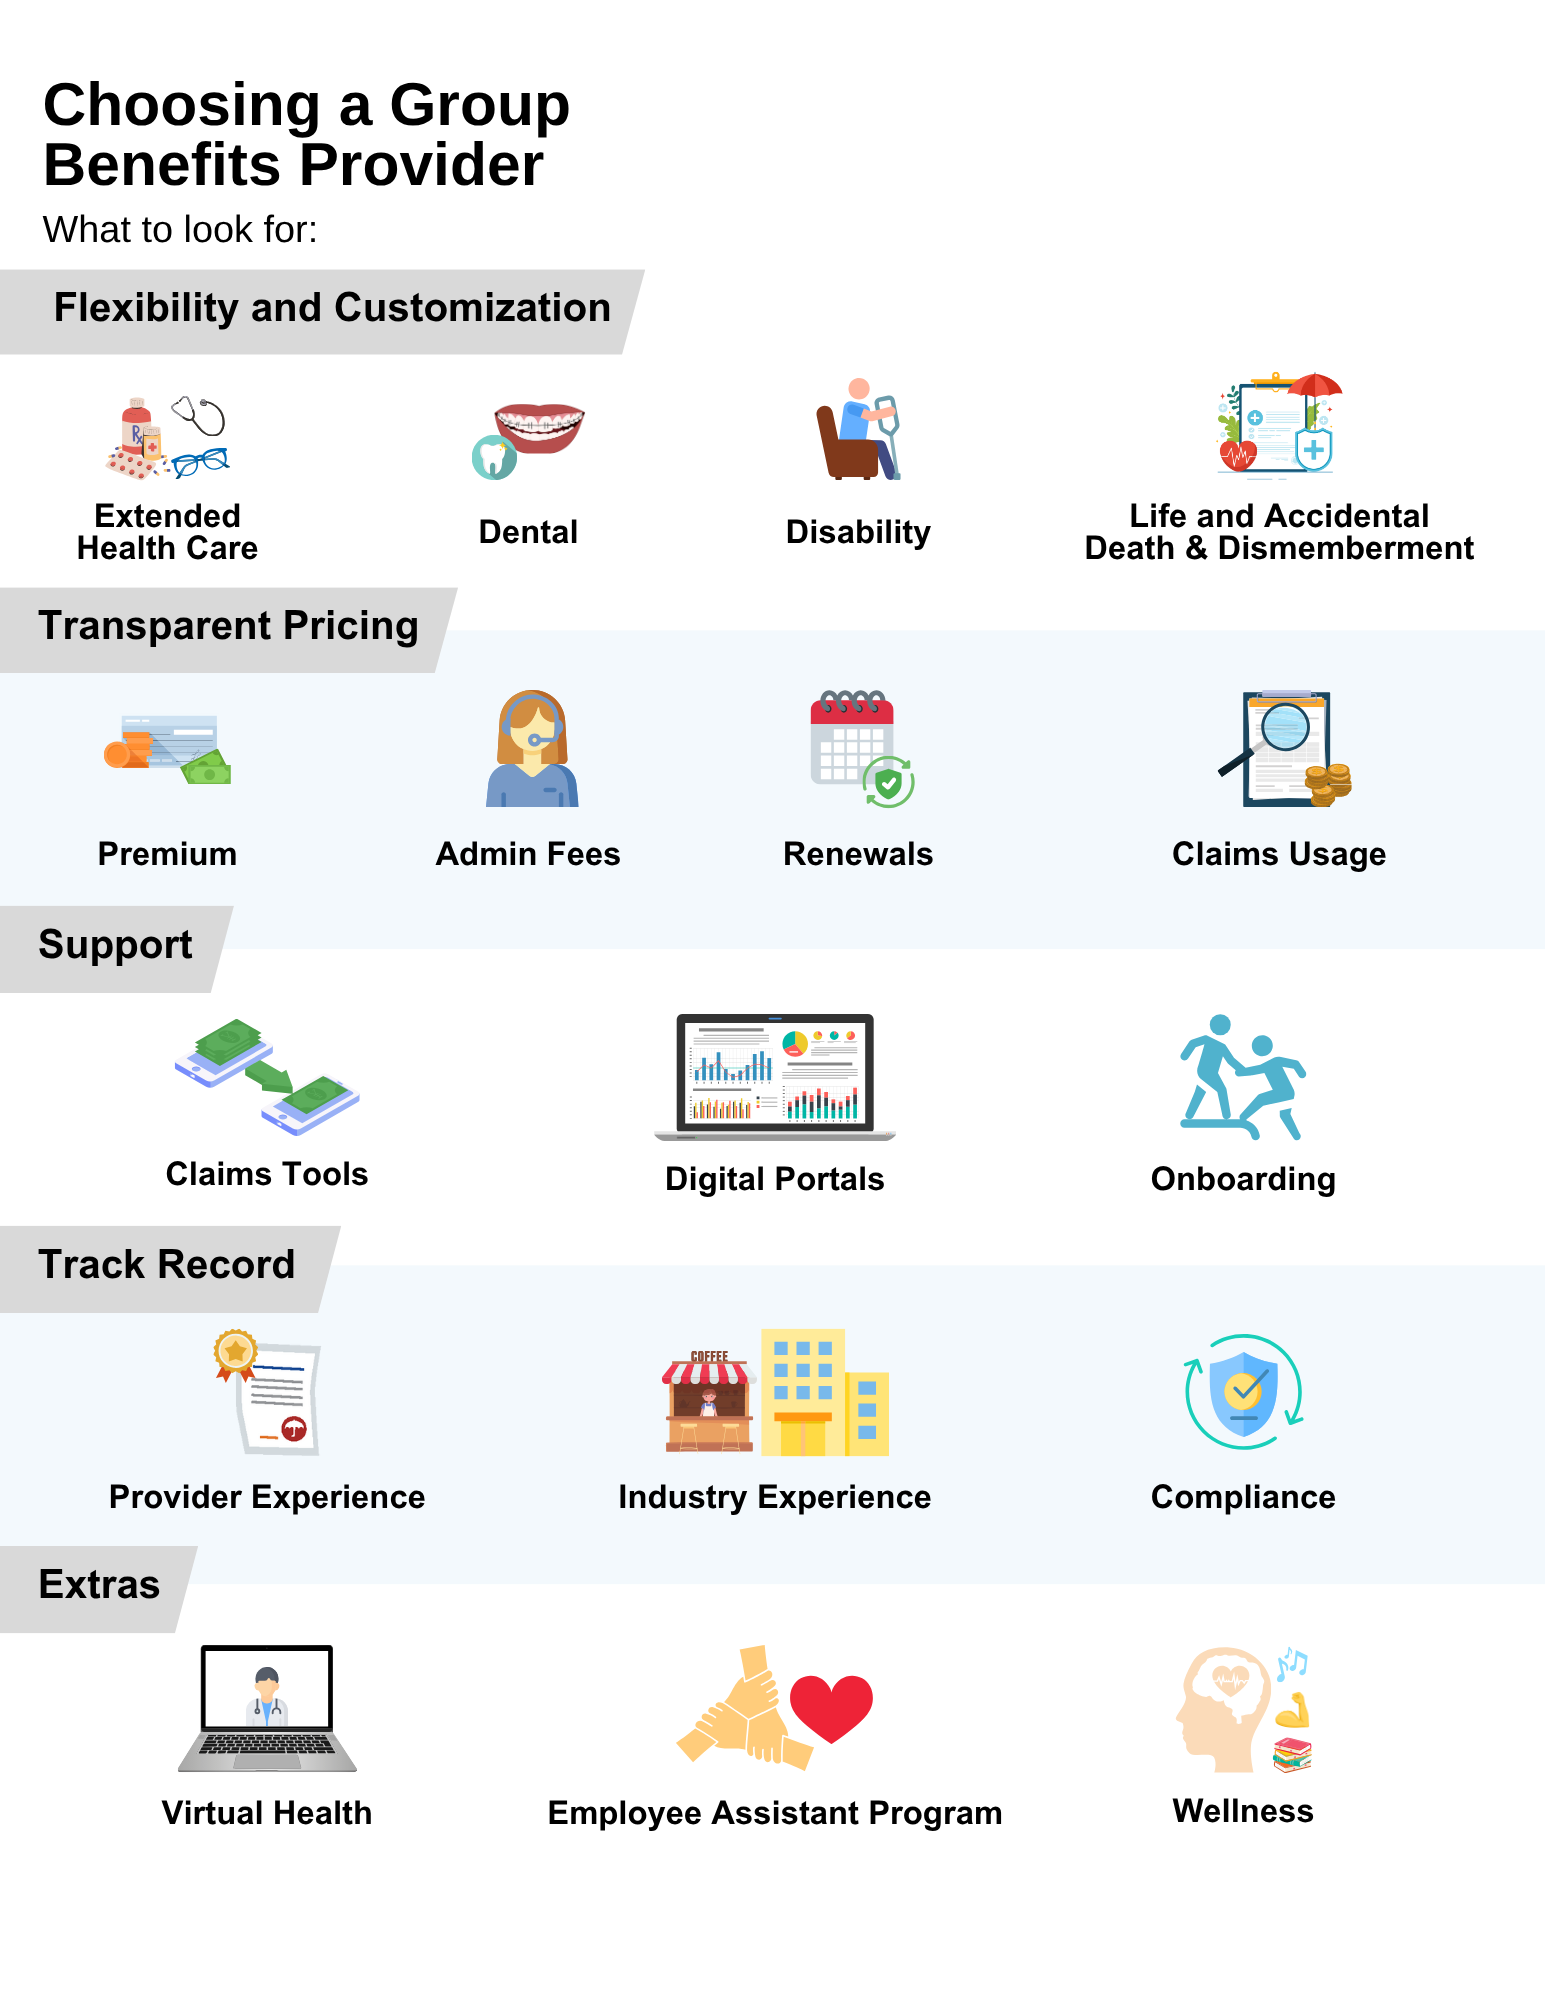
1. Flexibility and Customization Are Essential

No two businesses are the same. That’s why we work with providers that offer modular, customizable plans. Whether you’re scaling up, restructuring, or maintaining a lean team, we’ll help you find the right mix of core and value-added benefits.

We typically break benefits into three key categories:

Core Health Coverage

  • Extended Health Care: prescription drugs, vision, and paramedical services like physiotherapy or massage

  • Dental: including basic, major restorative, and orthodontics

  • Disability Insurance: both short- and long-term income protection

  • Life and Accidental Death and Dismemberment (AD&D) Insurance: Offers life insurance coverage for employees and their dependents, along with AD&D benefits in the event of a severe injury or accidental death

Additional Benefits

  • Critical Illness Insurance: lump-sum coverage for specified serious health conditions

  • Emergency Medical Travel Insurance: protection while traveling outside Canada

  • Health Spending Accounts and Wellness Spending Accounts

  • Employee Assistance Programs 

We tailor your plan based on your budget, team needs, and industry benchmarks¹.

2. Transparent Pricing and Clear Expectations

We help you make sense of what you’re really paying for. When we review provider proposals with our clients, we break down:

  • Premium costs and rate structures

  • Admin and service fees

  • Renewal practices and what drives pricing changes

  • Claims usage and cost control opportunities

As your partner, we advocate for your best interest and help avoid surprises at renewal².

3. Strong Support for Your Team and Admin Staff

We only recommend providers that make life easier for both your employees and your internal team. That includes:

  • Mobile and desktop-friendly claims tools

  • Clear digital portals for both employees and plan administrators

  • Helpful onboarding and documentation

We also provide ongoing support after implementation—especially during renewals or changes in your workforce.

4. A Trusted Track Record in the Canadian Market

We’ve worked with a wide range of providers over the years and have seen firsthand what sets the best apart. When we evaluate who to recommend, we draw on both our industry knowledge and direct client experience. We look at:

  • Their track record serving Canadian businesses across various regions

  • Their ability to support companies in your specific industry or business size

  • Client references, satisfaction feedback, and third-party reviews³

  • Consistent alignment with provincial and federal compliance requirements

Our recommendations are based on what we’ve seen work—not just what’s on paper. We only suggest providers who’ve proven themselves reliable, responsive, and supportive in real-world situations.

5. Extras That Truly Support Employee Wellbeing

Benefits plans aren’t just about insurance anymore. We help you evaluate added features that can increase employee engagement, including:

  • Virtual healthcare and mental health tools

  • Employee Assistant Programs with access to counselling and wellness resources

  • Financial wellness programs

Employers that prioritize wellbeing tend to see stronger engagement, lower absenteeism, and improved workplace culture⁴.

Let’s Build a Plan That Works

As independent group benefits specialists, we’re not tied to any one provider. That means we work for you, not the insurance company. Our role is to simplify the process, compare the best options, and help you build a benefits program that supports your people—and your business.

Whether you’re starting fresh, reviewing your current plan, or just want a second opinion, we’re here to help.

Let’s talk.

We’d love to learn more about your team and walk you through how we can help you build a benefits plan that fits—now and as you grow.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Sources: 

  1. Canadian Life and Health Insurance Association. Employee Benefits: CLHIA. CLHIA, 2023, www.clhia.ca/web/CLHIA_LP4W_LND_Webstation.nsf/page/EmployeeBenefits

  2. Financial Consumer Agency of Canada. Financial Literacy for Canadian Business Owners. Government of Canada, 2024, www.canada.ca/en/financial-consumer-agency.html

  3. Benefits Canada. Home Page. Benefits Canada, 2025, www.benefitscanada.com/

  4. Sun Life. “Sun Life Wellness Report Shows Employee Well-Being Is Key to Business Success.” Sun Life Newsroom, 2023, www.sunlife.ca/en/about-us/newsroom/news-releases/2023/sun-life-wellness-report-shows-employee-well-being-is-key-to-business-success/.

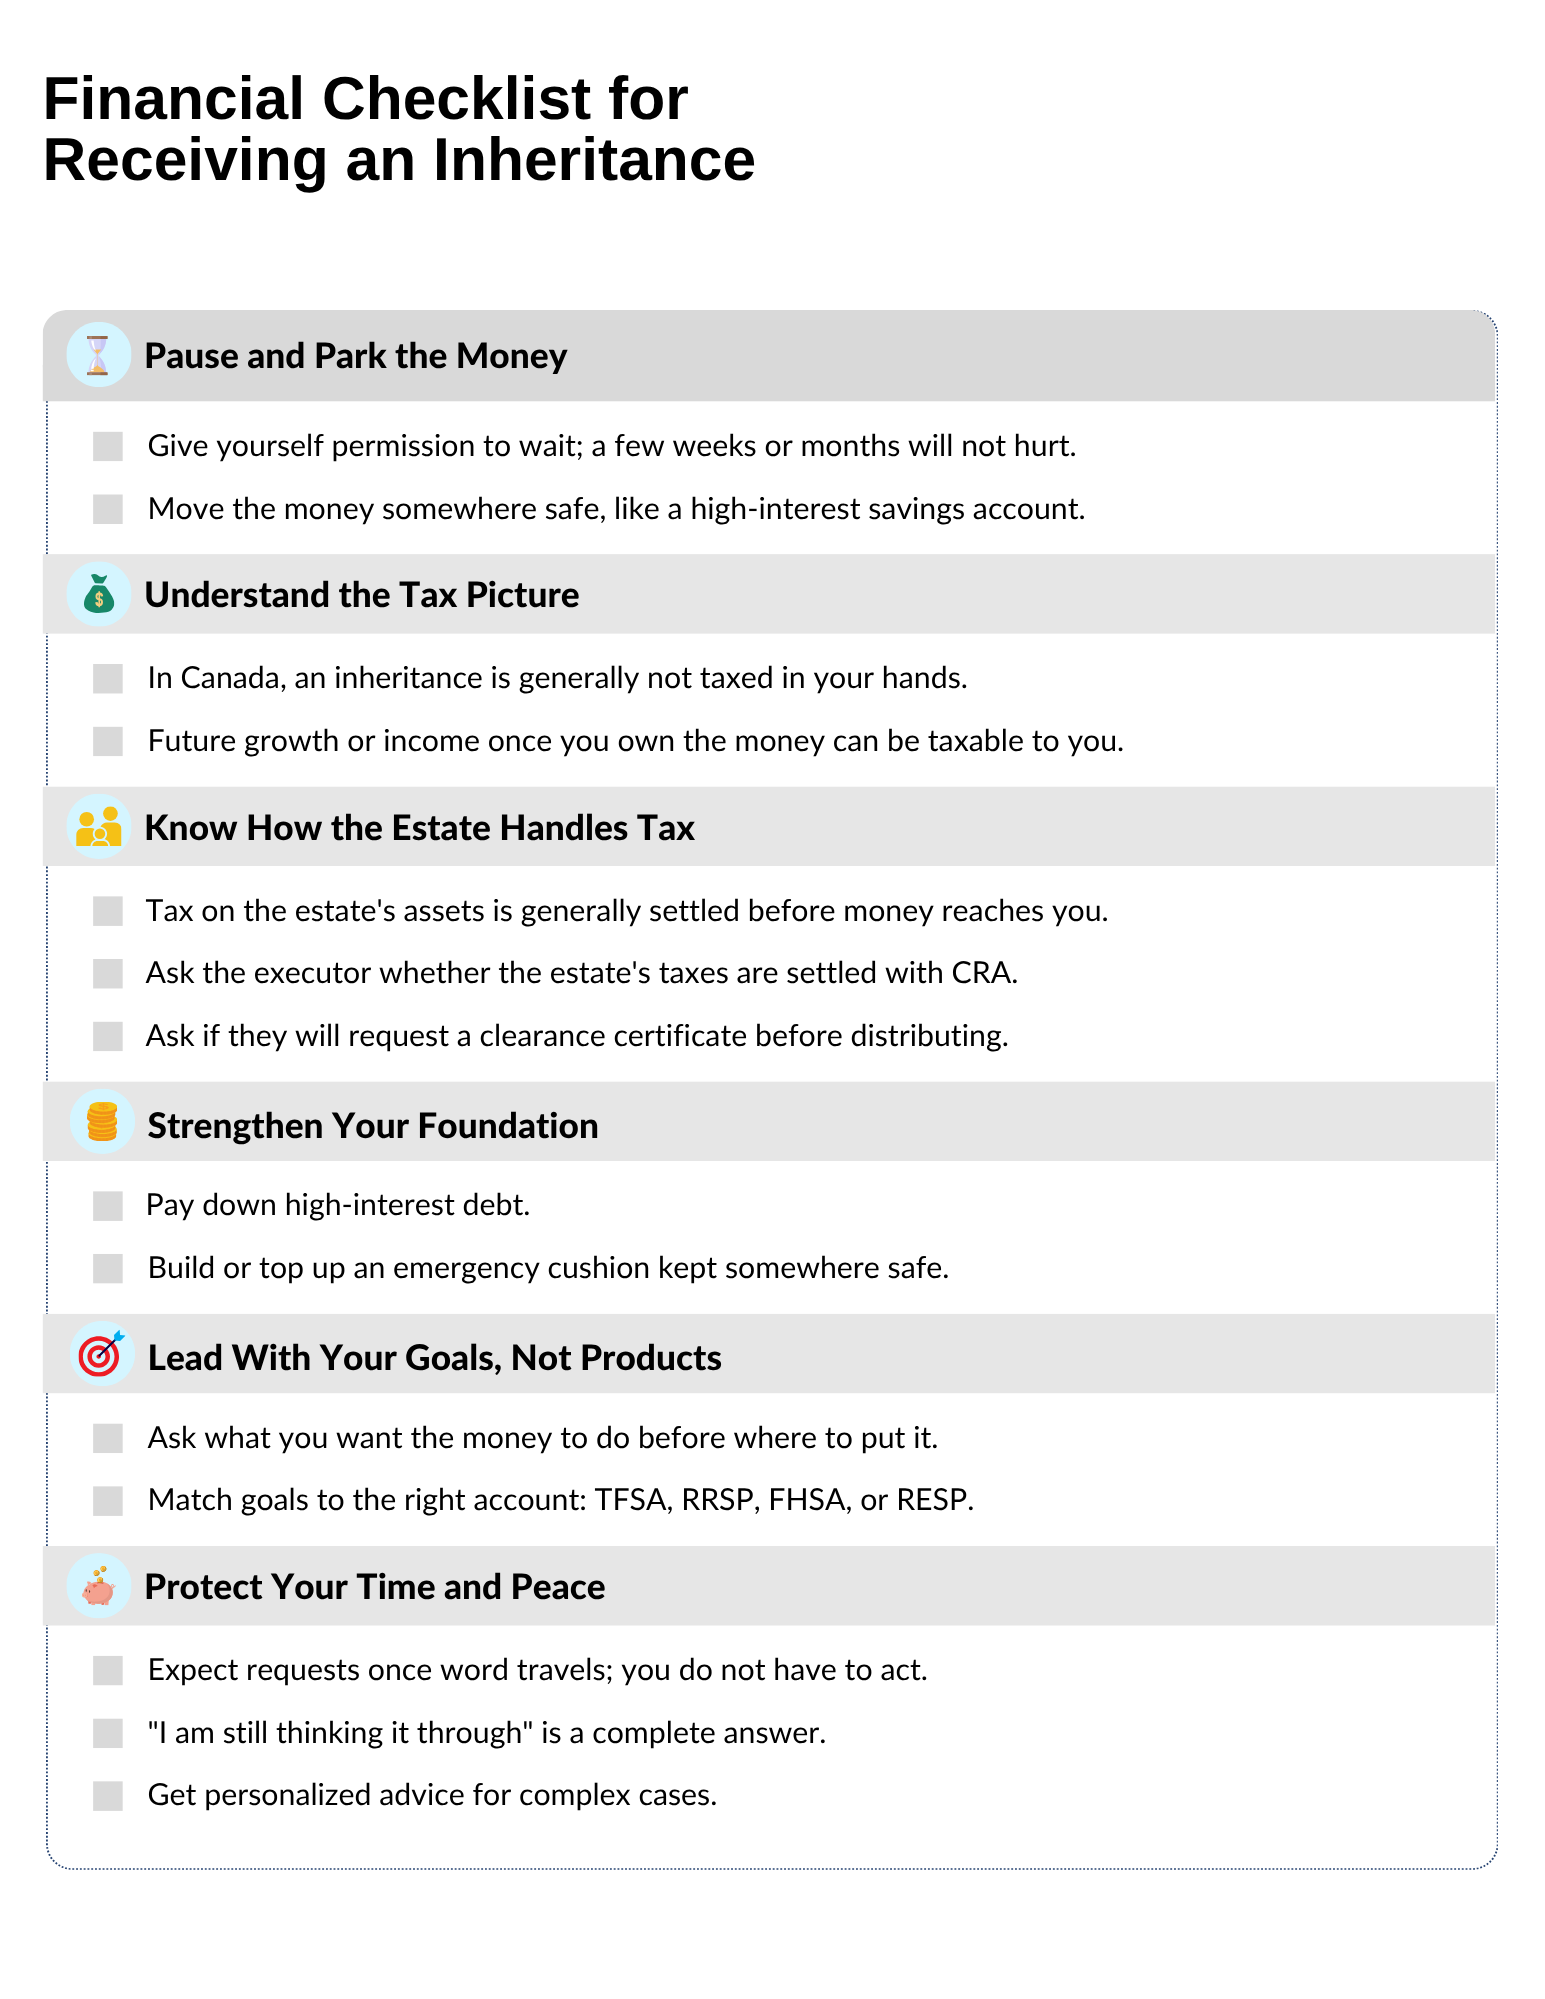
You Just Inherited Money: What to Do First

You Just Inherited Money: What to Do First

Coming into an inheritance is a strange mix of feelings. There is often grief, because the money usually comes after losing someone you care about. There can also be relief, pressure, or even guilt. On top of all that, you may feel a quiet panic about doing the right thing with the money.

Here is the good news. You have more time than you think. The smartest first move is almost never a big move. Let us walk through what to do first, one calm step at a time.

First, Pause and Park the Money

There is no rush. Money that has been waiting in an estate is not going anywhere, and a few weeks or months of thinking time will not hurt you. In fact, that pause can save you from choices you might regret.

When a large sum lands in your account, it can feel like you should do something with it right away. Resist that pull. Big decisions made in the early days of grief or excitement are often the ones people wish they could undo.

For now, put the money somewhere safe and boring. A high-interest savings account is a good home. Your money stays easy to reach, it is protected, and it earns a bit while you think. There is no need to invest it, lend it, or spend it until you have had time to plan with a clear head.

Understand the Tax Picture

This part surprises a lot of people, in a good way. In Canada, an inheritance is generally not taxed in the hands of the person who receives it. You usually do not report the money you inherit as income, and you do not pay tax just for receiving it.

Why is that? Because the tax is generally settled by the estate before the money reaches you. When someone passes away, their final tax return is prepared, and any tax owing on their assets is handled at that stage. The money is usually distributed to family and other heirs after that step. So by the time it gets to you, the tax piece has generally already been dealt with.

This does not mean money you inherit is tax-free forever. Once you own it, any future growth, interest, or income it earns can be taxable to you, just like your other money. But the act of inheriting it, on its own, generally does not create a tax bill for you.

brandableContent

How Assets Are Treated in the Estate

For most people receiving an inheritance, the reassuring part is that this tax work happens at the estate level, not yours. You usually do not pay tax just for receiving an inheritance. If you would like to understand what happens behind the scenes, here is what happens to different assets before they reach you. The rules depend on the type of asset.

For non-registered assets, such as an investment account or a property that is not a primary home, assets are generally deemed disposed at fair market value on death, and accrued gains are reported on the final return unless a spousal rollover applies. The rollover works like this: these assets can roll to a spouse or common-law partner, or a qualifying spousal trust, on a tax-deferred basis. Otherwise, the accrued gain is reported on the final return.

For an RRSP or RRIF, the full value is generally treated as received and added to income on the final return, except where a spouse or common-law partner is a successor annuitant or receives an eligible rollover, or where a financially dependent child or grandchild qualifies for a rollover.

For a TFSA, growth inside a TFSA is tax-free to the date of death. A spouse or common-law partner named as successor holder can continue it tax-free, where that option is available. A named beneficiary follows set steps, and later growth can be taxable.

One simple thing is worth doing as a beneficiary: it is fair to ask the executor whether the estate’s taxes are settled, and whether they have requested a clearance certificate, before the estate is fully wound up. A clearance certificate is CRA’s confirmation that the estate’s taxes are paid, and it is something the executor may want to request before distributing the estate.

Pay Down Debt and Shore Up Savings

Once you have paused and you understand the tax basics, you can start to think about using the money well. Two steps tend to give the best return for the least worry.

The first is paying down high-interest debt. Credit card balances and other costly loans can quietly drain your budget every month. Clearing them is like giving yourself a guaranteed return, because you stop paying that interest for good. Few investments can promise that.

The second is building or topping up an emergency cushion. This is simply cash set aside for surprises, kept somewhere safe and easy to reach, like that high-interest savings account. A solid cushion means the next car repair or job hiccup does not throw your life off track. Together, clearing costly debt and holding a cash buffer give you a calm, steady base before you do anything fancier.

Think About Goals Before Products

It is tempting to jump straight to “where should I put this money?” A better question is “what do I want this money to do for me?” Goals come first. Products come second.

Maybe you want to retire a little sooner, buy a first home, save for a child’s schooling, or just feel more secure. Once your goals are clear, registered accounts can help you reach them, and each one has a job:

  • A TFSA lets your savings grow tax-free, and you can take money out for any purpose.

  • An RRSP is built for retirement and can lower your taxable income in the year you contribute.

  • An FHSA is designed to help you save toward a first home.

  • An RESP helps you save for a child’s education after high school, with government grants that add to what you put in.

Each account has its own contribution room and rules, and these change over time. You can check your available room and the current limits through CRA My Account or at canada.ca. Matching the right account to the right goal is what turns a windfall into lasting progress.

If your situation involves cross-border elements, such as inheriting foreign property, or executors or beneficiaries in different countries, the tax picture can be more complex and may involve foreign reporting or foreign estate taxes. That is one of the times when personalized advice is well worth it.

Watch for Pressure and Take Your Time

A sudden sum of money can change how people treat you, and how you feel. Word travels. You may get requests for loans, gifts, or “can’t-miss” opportunities. You may also feel pressure inside your own family about what the money should be used for.

None of that means you must act. It is your inheritance, and you are allowed to take your time. A simple, kind answer works well: “I am still thinking it through.” That one sentence buys you space and protects you from rushed choices.

Coming into money you did not plan for is a lot to hold, especially when it follows a loss. So go gently. Park it somewhere safe, remember that your inheritance is generally not taxed to you when you receive it, and let your goals lead the way. The single best first step is often the simplest one: give yourself permission to pause. What would feeling truly settled with this money look like for you?

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

How to Catch Up on Your RRSP Contributions

How to Catch Up on Your RRSP Contributions

If you have ever felt behind on your RRSP, you are not alone. Life gets in the way, rent, a mortgage, kids, a period of lower income, and RRSP contributions get pushed to the back of the list.

Here is the good news: unused RRSP contribution room does not disappear. It accumulates year over year, and many Canadians are sitting on far more room than they realize. Catching up on those contributions is one of the most straightforward ways to reduce your tax bill.

Here is how it works.

What Is RRSP Contribution Room?

Each year, the Canada Revenue Agency (CRA) calculates how much you are allowed to contribute to your RRSP. The formula is 18% of your prior year’s earned income, up to an annual maximum set by the government, which is updated periodically and published by the CRA each year.

If you do not contribute the full amount in a given year, the unused room carries forward to the following year. And the year after that. And so on.

This carry-forward provision is what makes catch-up contributions possible. Someone who has been contributing inconsistently over the past decade may have accumulated tens of thousands of dollars in available room.

How to Find Your Contribution Room

The most reliable way to see your available RRSP room is through your CRA My Account, the federal government’s online portal. Once logged in, look for your Notice of Assessment (NOA) from last year’s tax return. Your RRSP deduction limit for the current year is listed there explicitly.

If you have not set up a CRA My Account, the same information appears on the paper NOA mailed to you after your return is processed. You can also call the CRA directly to confirm your available room.

Your available room is the combined total of any room you did not use in prior years, plus the new room added based on last year’s income.

The Tax Benefit of Catching Up

RRSP contributions reduce your taxable income dollar for dollar. If you are in a 40% combined federal and provincial marginal tax bracket and contribute $10,000 to your RRSP, you reduce your taxable income by $10,000, which means approximately $4,000 less in taxes owed.

That is the core value of catching up. Every dollar of unused room you do not use is a tax deduction sitting on the table.

The benefit compounds over time as well. Money contributed to your RRSP grows tax-sheltered until withdrawn. The earlier it is contributed, the longer it has to grow without being taxed each year.

The RRSP Catch-Up Loan Strategy

One approach many Canadians use is an RRSP catch-up loan, a short-term personal loan taken specifically to make a large RRSP contribution all at once.

Here is the idea: you borrow a lump sum, deposit it into your RRSP before the deadline, and use the tax refund you receive to pay down a significant portion of the loan. If your refund covers half the loan, for example, you are left with only half the balance to pay off over the following months.

This strategy works best when:

  • You have a meaningful amount of carry-forward room built up

  • You are in a higher tax bracket, which produces a larger refund

  • You can realistically pay off the loan within 12 months

The interest on an RRSP loan is not tax-deductible, so the goal is to repay it quickly. Holding the loan for an extended period reduces the overall benefit of the strategy.

Many Canadian banks and credit unions offer RRSP loans specifically for this purpose, often at competitive rates and with repayment terms designed around the expected tax refund timeline.

Timing: The RRSP Deadline

RRSP contributions for a given tax year must be made by 60 days after December 31, which works out to March 1 in most years, or March 2 when the following year is a leap year. Contributions made in January or February of the new year can be applied to either the previous tax year or the current one, giving you some flexibility.

Many Canadians wait until close to the deadline to contribute. While this is common, making contributions earlier in the year, or throughout the year, means the money spends more time growing inside the plan.

Over-Contributing: What to Watch

There is one important guard rail: RRSP over-contributions above a $2,000 lifetime buffer are penalized at 1% per month on the excess amount. This rarely happens accidentally, but it is worth confirming your available room before making a large lump-sum deposit.

Your confirmed room from your most recent NOA, minus any contributions already made in the current year, gives you your remaining available room.

When an RRSP Makes the Most Sense

The RRSP is most valuable when you are in a higher tax bracket now than you expect to be in retirement. Contributing while earning at a high rate and withdrawing at a lower rate in retirement produces the greatest tax advantage.

If you are in a lower bracket now, it can sometimes make more sense to contribute to a TFSA first and save your RRSP room for higher-earning years. Both accounts have their place, and many Canadians use both, the RRSP for the tax deduction today, the TFSA for tax-free access later.

Putting It Together

If you have years of unused RRSP room, that room represents real tax savings that are still within reach. Catching up does not require a windfall. It can be done gradually, contributing more each year than required, or all at once using a short-term loan.


Check your CRA My Account for your current room, run the numbers on what a contribution would mean for your tax return this year, and decide whether catching up makes sense for your situation. The deadline comes every early March, and with every year that passes, the carry-forward room keeps growing.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

What Is Participating Whole Life Insurance?

What Is Participating Whole Life Insurance?

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.

Here is what it means, how it works, and whether it might be a fit for you.

Permanent Coverage That Does Not Expire

Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.

That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.

With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.

How Dividends Work

The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.

These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.

When you receive a dividend, you have a few options for how to use it:

  • Take it as cash. The dividend is paid to you directly.

  • Apply it to your premium. It reduces how much you pay out of pocket.

  • Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.

  • Leave it on deposit. The dividend sits with the insurer and earns interest.

Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.

The Cash Value

One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.

The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:

  • Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.

  • Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.

The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.

Who Is This Type of Policy For?

Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.

Some of the most common situations where it makes sense:

Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.

Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.

Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.

High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.

How It Fits Alongside Term Insurance

Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.

Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.


Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.

What to Take Away

Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.

If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.

Sources:

Participating Life Insurance – CLHIA

What Is Life Insurance and How Does It Work?

What Is Life Insurance and How Does It Work?

Have you ever wondered what would happen to your family’s finances if you were no longer here? It’s not an easy thought. But it is an important one. Life insurance is designed to protect the people you care about most if something unexpected happens.

Many people avoid this topic because it feels uncomfortable or confusing. The good news is that life insurance is actually quite simple once you break it down.

What Is Life Insurance?

Life insurance is a contract between you and an insurance company. You pay a regular payment called a premium. In return, the insurance company agrees to pay a lump sum of money to someone you choose (your beneficiary) if you pass away.

That lump sum is called a death benefit. In most cases, it is paid tax-free to your beneficiary.

Think of life insurance like a safety net. You hope it is never needed. But if it is, it can help your family stay financially stable during a very difficult time.

Millions of Canadians have some form of life insurance coverage. For many families, it plays an important role in protecting income and covering large expenses.

How Does Life Insurance Work?

The process is straightforward.

First, you apply for coverage. The insurance company reviews details such as your age, health, lifestyle, and sometimes your occupation. This helps them decide your premium and whether you qualify.

Once approved, you begin paying premiums. As long as you keep paying, your coverage remains active.

If you pass away while the policy is active, your beneficiary files a claim. The insurance company reviews the claim and then pays out the death benefit.

Your beneficiary can use the money for any purpose, such as:

  • Paying off a mortgage

  • Covering funeral expenses

  • Replacing lost income

  • Paying off debt

  • Supporting children’s education

The goal is to reduce financial stress at a time when your family is already dealing with emotional loss.

The Two Main Types of Life Insurance

Most people choose between two main types of coverage: term life insurance and permanent life insurance.

Term Life Insurance

Term life insurance covers you for a set period of time, such as 10, 20, or 30 years.

It is usually the most affordable option, especially for young families. If you pass away during the term, the policy pays out. If the term ends and you are still living, the coverage ends unless you renew it.

Term insurance works well for temporary needs. For example:

  • Protecting your income while your children are young

  • Covering a mortgage while the balance is high

  • Replacing income during your working years

It is simple and focused on protection.

Permanent Life Insurance

Permanent life insurance covers you for your entire lifetime, as long as premiums are paid.

It also includes a savings feature called cash value. Over time, this value can grow on a tax-deferred basis.

Permanent coverage is usually more expensive than term coverage. However, it can support longer-term goals such as:

  • Covering final expenses

  • Leaving money to family or a charity

  • Helping manage taxes at death

  • Supporting estate planning goals

The right type of coverage depends on your needs, timeline, and budget.

How Much Coverage Do You Need?

This is one of the most common questions people ask.

A good starting point is to ask: If I were gone tomorrow, what financial gap would my family face?

You may want to consider:

  • Your mortgage balance

  • Other debts

  • Ongoing living expenses

  • Childcare costs

  • Future education expenses

  • Final expenses

Some people use a simple guideline like 10 times their annual income. But that is only a starting point. Your personal situation matters more than any rule of thumb.

For example, someone with no dependents and little debt may need very little coverage. A household with young children and a large mortgage may need much more.

The goal is to match coverage with real responsibilities.

Is Life Insurance Expensive?

Many people assume life insurance costs more than it does. In reality, term coverage can be very affordable, especially if you are young and in good health.

Your premium is based on factors such as:

  • Age

  • Health history

  • Smoking status

  • Coverage amount

  • Type of policy

The younger and healthier you are when you apply, the lower your premium is likely to be.

Waiting can increase the cost. Health can change over time. Securing coverage earlier can help lock in lower rates.

Who Should Consider Life Insurance?

Life insurance is not necessary for everyone. But it is important for many people.

You may want to consider coverage if:

  • Someone depends on your income

  • You share debts with a partner

  • You have children

  • You own a home

  • You want to leave money behind for loved ones

Even stay-at-home parents may need coverage. If they were not there, the cost of childcare and household support could be significant.

In Canada, life insurance benefits are generally paid tax-free to beneficiaries. This helps ensure that the full amount can be used for its intended purpose.

Final Thoughts

Life insurance is a practical tool. It helps protect the people you care about from financial hardship if something unexpected happens. It can provide stability, cover major expenses, and support your family’s future.

If you are unsure whether you need coverage, start by reviewing who depends on you and what financial responsibilities you carry. A short conversation can bring clarity and peace of mind.

If you would like to explore how life insurance fits into your overall strategy, I would be happy to guide you through the options and help you make an informed decision.

This is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Tax Lines to Look Out For on Your 2025 Canadian Tax Return

Tax Lines to Look Out For on Your 2025 Canadian Tax Return

The deadline for filing your 2025 income tax return is April 30, 2026. With several changes this year, from a lower federal tax rate to new benefits and eliminated credits, it pays to know what has changed before you file. This guide covers the key updates, deductions, and credits separated into sections for Individuals and Families, and Self-Employed Individuals.

For Individuals and Families

Federal Tax Rate Reduction

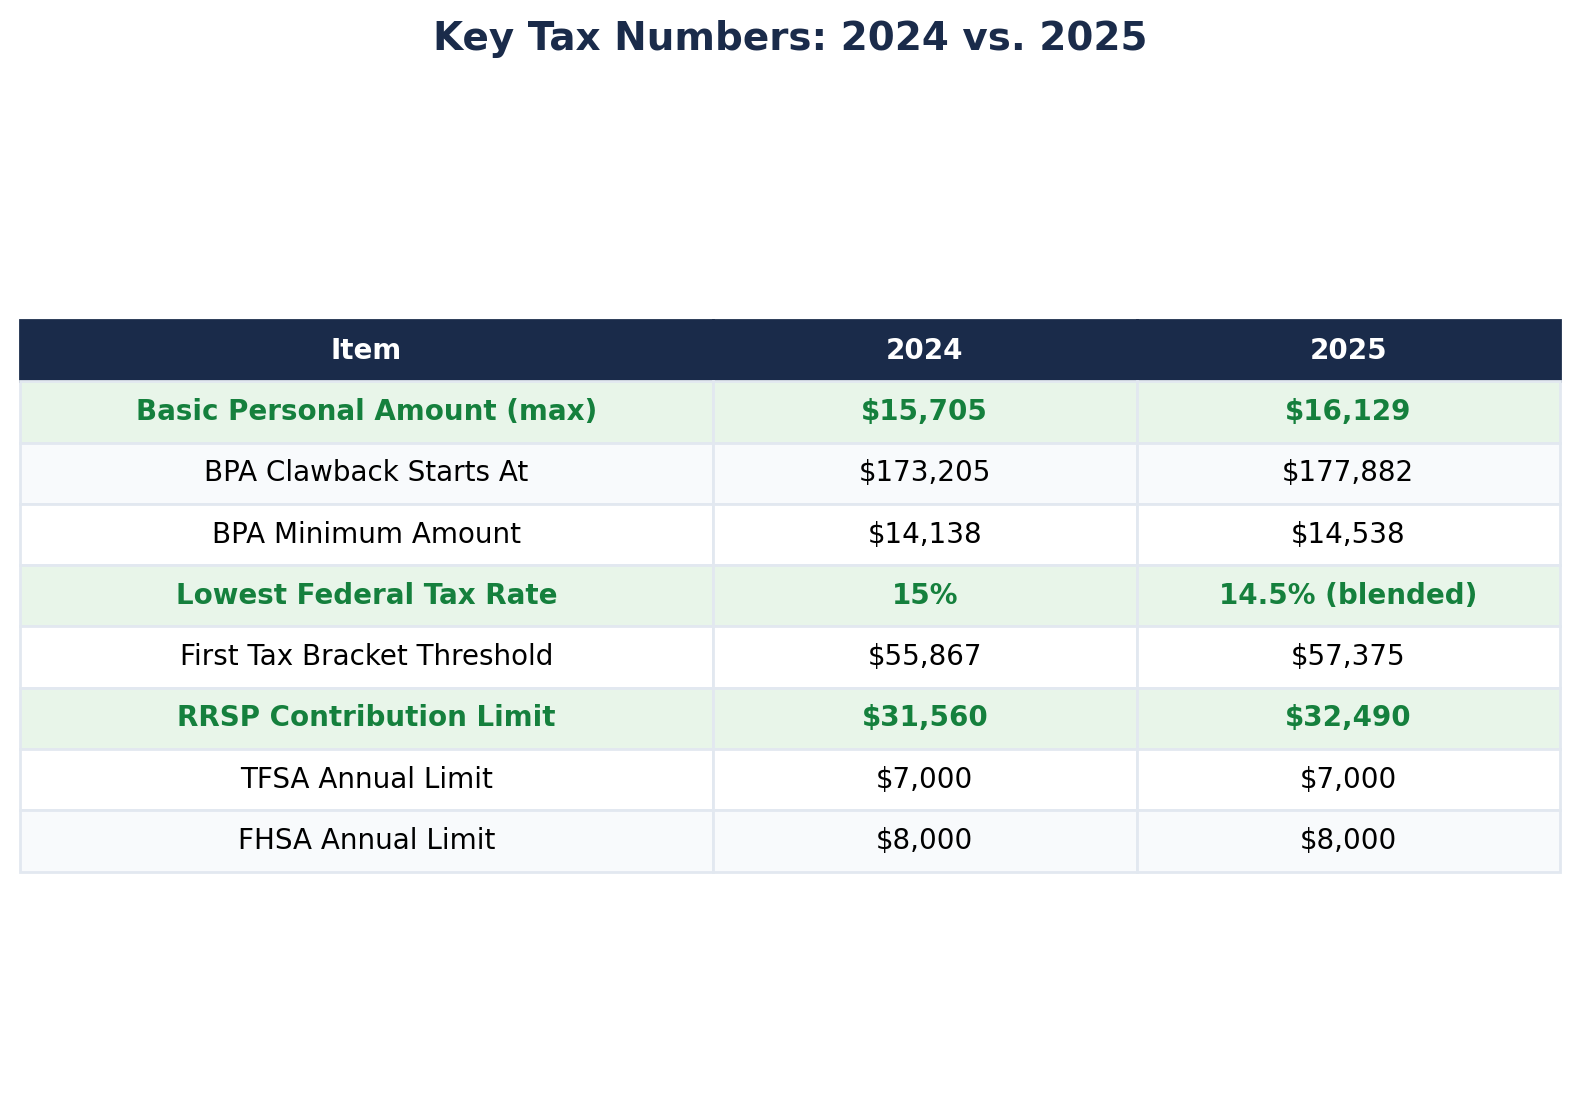
Effective July 1, 2025, under draft legislation introduced May 27, 2025, the lowest federal income tax rate was reduced from 15% to 14%. Because this change took effect halfway through the year, the blended rate for 2025 is 14.5%. This applies to the first $57,375 of taxable income and could save an individual up to $420 per year, or up to $840 for a two-income household.

Because the lowest rate also determines the value of most non-refundable tax credits, the government introduced a new top-up credit. This credit restores the full 15% value on eligible non-refundable credits claimed on amounts above $57,375, so the rate cut does not reduce the value of credits like the Basic Personal Amount, medical expenses, or tuition. This top-up credit will remain in place through the 2030 tax year.

Basic Personal Amount (BPA)

For 2025, the Basic Personal Amount has increased to $16,129 for taxpayers with net income up to $177,882. For those with net incomes above this amount, the BPA is gradually reduced, reaching a minimum of $14,538 at incomes of $253,414 or higher.

Capital Gains

The proposed increase in the capital gains inclusion rate from 50% to 66.67% on gains over $250,000 for individuals (and on all gains for corporations and most trusts) has been cancelled. The inclusion rate remains at 50% for all taxpayers. However, the lifetime capital gains exemption has been raised to $1,250,000 for qualifying dispositions of small business shares and farming or fishing property, up from $1,016,836.

Canada Disability Benefit

A new benefit became available in June 2025, providing up to $200 per month ($2,400 per year) for Canadian residents aged 18 to 64 who are approved for the Disability Tax Credit.

The benefit is income-tested, with the maximum amount generally available to single individuals with adjusted family net income of $23,000 or less. For couples, the threshold is higher (generally $32,500 after a working income exemption).

The benefit is gradually reduced as income increases. For single individuals, it is typically reduced by 20 cents for each dollar above the threshold. For couples, the reduction may be 20% or split at 10% each, depending on whether one or both partners qualify for the benefit.

What Has Been Eliminated

Canadian Journalism Tax Credit: The 15% non-refundable tax credit for qualifying digital news subscriptions (up to $75 per year) is no longer available for 2025.

Home Accessibility and Medical Expense Double-Claim: Under proposed measures announced in Budget 2025 and included in Bill C-15, 2025 is expected to be the final year that certain expenses qualifying for the Home Accessibility Tax Credit can also be claimed as a medical expense. Starting in 2026, these expenses will generally need to be claimed under only one provision and cannot be double-counted. Individuals planning eligible renovations may wish to take advantage of the current rules before this change takes effect.

Alternative Minimum Tax (AMT)

The updated AMT rules that took effect in 2024 continue to apply. These include a higher minimum tax rate, modified calculation for adjusted taxable income affecting foreign tax credits and minimum tax carryovers, and limited value on most non-refundable tax credits.

Popular Tax Credits and Deductions

Canada Training Credit (CTC) Eligible taxpayers aged 26 to 65 can claim this refundable tax credit to cover a portion of eligible tuition and fees for training or courses to enhance their skills.

Canada Caregiver Credit (CCC) This non-refundable tax credit supports individuals caring for family members or dependents with a physical or mental impairment. The amount varies based on the dependent’s relationship, net income, and circumstances.

Child Care Expenses Child care expenses, such as daycare, nursery schools, day camps, and boarding schools, are deductible if incurred to enable a parent or guardian to work, pursue education, or conduct research.

Disability Tax Credit (DTC) The DTC provides a non-refundable tax credit for individuals with disabilities or their caregivers to reduce the amount of income tax payable. For 2025, the disability amount is $10,138. Applicants must have a certified disability lasting at least 12 months. The expenses eligible for the disability supports deduction have also been expanded for 2025.

Moving Expenses Deductible moving expenses include transportation and storage costs, travel expenses, temporary living costs, and incidental expenses incurred when relocating at least 40 kilometers closer to a new work location, educational institution, or business location.

Interest Paid on Student Loans Interest paid on eligible student loans can be claimed as a non-refundable tax credit. The loans must be under federal, provincial, or territorial student loan programs.

Donations and Gifts Donations made to registered charities or other qualified organizations qualify for non-refundable federal and provincial tax credits. Typically, eligible amounts up to 75% of net income can be claimed. Note: due to the Canada Post strike in late 2024, eligible donations made in the first two months of 2025 can also be claimed on a 2024 return.

GST/HST Credit The GST/HST credit is a quarterly refundable payment designed to offset the impact of sales tax on low to moderate-income individuals and families. Eligibility is automatically assessed based on the annual tax return.

RRSP Contributions The maximum RRSP contribution for 2025 has increased to $32,490 (up from $31,560 in 2024), based on 18% of the previous year’s earned income. The TFSA annual contribution limit remains at $7,000 for 2025.

First Home Savings Account (FHSA) Contributions of up to $8,000 per year (lifetime limit of $40,000) are tax-deductible, grow tax-free, and qualifying withdrawals for a first home purchase are also tax-free. The FHSA can be used alongside the Home Buyers’ Plan, which maintains a withdrawal limit of $60,000.

For Self-Employed Individuals

CPP Contributions

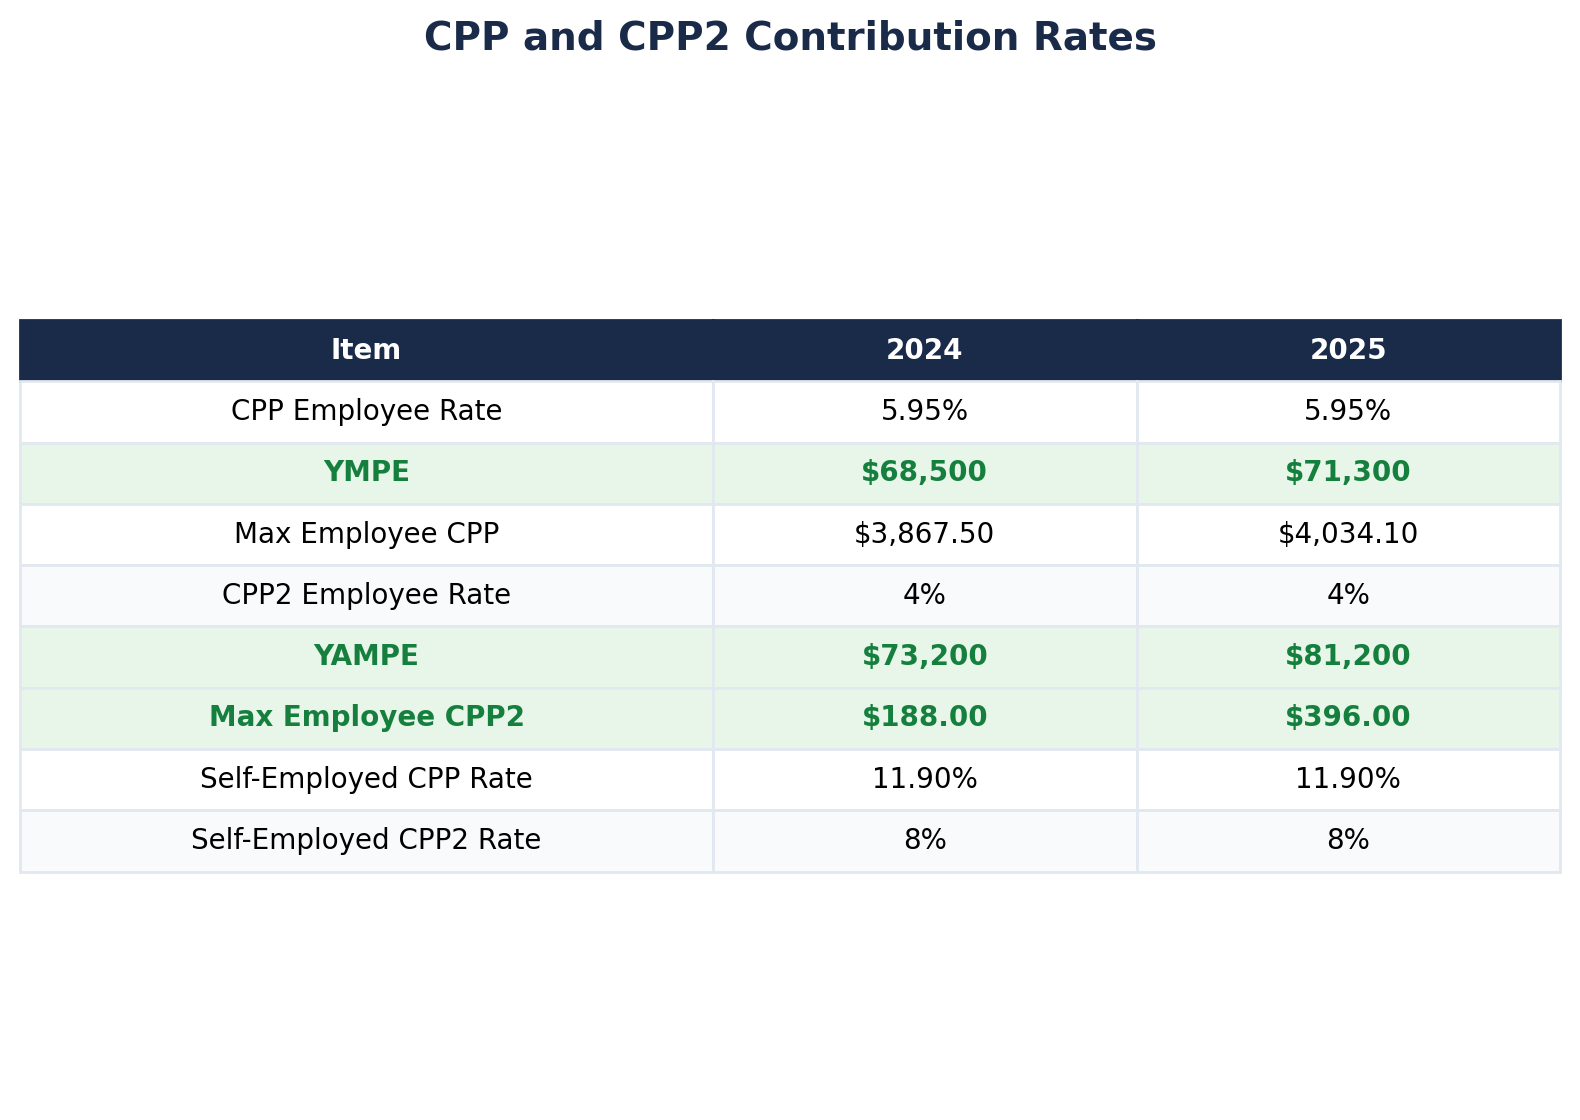
Self-employed individuals pay both the employee and employer portions of CPP, for a combined rate of 11.90% on earnings up to the YMPE ($71,300). For CPP2, the self-employed rate is 8% on earnings between $71,300 and $81,200, with a maximum CPP2 contribution of $792.

Filing and Payment Deadlines

  • Tax Return Deadline: June 15, 2026.

  • Balance due must be paid by April 30, 2026.

Reporting Business Income

Report income on a calendar-year basis for sole proprietorships and partnerships.

Digital Platform Operators

Reporting rules require platform operators to collect and report seller information to the CRA. If income is earned through a digital platform, it is important to ensure it is properly reported.

Filing season for 2025 returns opens February 23, 2026. With a lower federal tax rate, increased contribution limits, and several eliminated credits and taxes, reviewing these changes before filing can help maximize savings and avoid surprises. The CRA is also no longer mailing paper tax packages, so returns and forms are available online at canada.ca or by calling 1-855-330-3305.

Sources

Canada Revenue Agency. “Personal income tax: What’s new for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/whats-new.html

Canada Revenue Agency. “Important changes to the 2025 income tax package.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2025/important-changes-2025-income-tax-package.html

Canada Revenue Agency. “Maximum Pensionable Earnings and Contributions for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2024/canada-revenue-agency-announces-maximum-pensionable-earnings-contributions-2025.html

Canada Revenue Agency. “Basic Personal Amount.” – Canada.ca – https://www.canada.ca/en/revenue-agency/programs/about-canada-revenue-agency-cra/federal-government-budgets/basic-personal-amount.html

Canada Revenue Agency. “Tax rates and income brackets for individuals.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/frequently-asked-questions-individuals/canadian-income-tax-rates-individuals-current-previous-years.html

“Budget 2025 – Tax Measures” (Home Accessibility Tax Credit change) – https://budget.canada.ca/2025/report-rapport/tm-mf-en.html

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

2026 Canada Money Facts

brandableContent

Staying informed about financial limits and government benefits is essential for effective planning. The 2026 Canada Money Facts infographic provides a clear snapshot of key savings limits and retirement benefits, including TFSA, RRSP, FHSA, RESP, CPP, and OAS.
Here’s what you need to know for 2026.

Tax-Free Savings Account (TFSA)

The 2026 TFSA contribution limit is $7,000, bringing the cumulative contribution room to $109,000 for individuals who have been eligible since the TFSA was introduced in 2009 and have never contributed.

It’s important to note that total TFSA room depends on personal circumstances. Eligibility begins at age 18 or 19, depending on the province, and newcomers to Canada accumulate room only from the year they become residents. If you became eligible after 2009, your cumulative limit will be lower based on the years you qualified.

The TFSA remains one of the most flexible savings tools available, allowing investments to grow tax-free and withdrawals to be made without triggering tax.

Registered Retirement Savings Plan (RRSP)

For 2026, the RRSP contribution limit is $33,810, calculated as 18% of earned income from the prior year, up to the annual maximum. To fully maximize RRSP contributions for 2026, an individual would need prior-year earned income of approximately $187,833.

RRSPs continue to be a cornerstone of retirement planning, offering tax-deductible contributions and tax-deferred growth, which can be especially valuable during higher-income earning years.

First Home Savings Account (FHSA)

The FHSA annual contribution limit remains $8,000 in 2026, with a cumulative contribution limit of $32,000.

As with previous years, FHSA eligibility begins at the age of majority (18 or 19, depending on the province), and contributions can only be made once the account is opened. Since the FHSA was introduced in 2023, not everyone will have access to the full cumulative room.

FHSA contributions are tax-deductible, and qualifying withdrawals for a first home purchase are tax-free, making this account a powerful planning tool for first-time homebuyers.

Registered Education Savings Plan (RESP)

RESP limits remain unchanged in 2026:

  • Lifetime contribution limit: $50,000 per beneficiary

  • Annual Canada Education Savings Grant (CESG): up to $500

  • Lifetime CESG maximum: $7,200

RESPs continue to be an effective way to save for a child’s post-secondary education while benefiting from government grants and tax-deferred growth.

Canada Pension Plan (CPP) & Old Age Security (OAS)

CPP benefit amounts increase for 2026:

  • Maximum CPP retirement benefit: $18,091 annually

  • Maximum CPP disability benefit: $20,894 annually

Actual CPP payments depend on an individual’s contribution history and the age at which benefits begin, but these figures provide a useful benchmark for planning purposes.

OAS payments for January 2026 are estimated at:

  • Ages 65–74: up to $8,907 annually

  • Ages 75+: up to $9,798 annually

OAS is subject to a clawback for higher-income retirees. In 2026, the clawback begins when 2025 net income exceeds $93,454. Full clawback thresholds are approximately $152,062 for ages 65–74 and $157,923 for ages 75 and over. OAS benefits are reduced by 15% of income above the threshold.

This 2026 infographic is designed as a quick reference to help Canadians stay informed and make confident planning decisions. Whether you’re maximizing registered accounts, preparing for retirement income, or saving for a home or education, understanding these updated limits helps ensure you’re making the most of available opportunities.

Staying proactive and informed in 2026 can make a meaningful difference in your long-term financial success.

Alberta Budget 2026

Alberta’s 2026 provincial budget was tabled on February 26, 2026. The government projects a deficit of $4.1 billion for 2025–26, $9.4 billion for 2026–27, and $7.6 billion for 2027–28. The budget does not introduce any new personal or corporate income tax rate increases. However, it includes several targeted tax measures that affect households, property owners, and businesses.

Below is a summary of the main tax and levy changes.

Personal Income Tax Rates Remain Unchanged

The 2026 budget does not change Alberta’s personal income tax structure. Alberta’s existing six‑bracket system, with a bottom rate of 8% and a top rate of 15%, remains in place for 2026, with normal indexation applied to the bracket thresholds.

The budget does not change the way capital gains, eligible dividends, or non‑eligible dividends are taxed at the provincial level. No changes were announced to the basic personal amount or Alberta’s indexation policy for provincial income tax.

Corporate Income Tax Rates Remain the Same

The budget does not introduce changes to corporate income tax rates.

For 2026:

  • The Alberta small business tax rate remains 2% on the first $500,000 of active business income.

  • The general corporate tax rate remains 8%.

  • The combined federal and Alberta corporate tax rate is about 11% for eligible small business income and about 23% for general active business income.

  • There are no changes to the $500,000 small business limit.

Alberta Caregiver Credit Introduced for 2027

The budget introduces a new Alberta Caregiver Credit effective for the 2027 and subsequent tax years.

This credit will replace the existing caregiver credit and infirm dependent credit. It will be available to individuals who care for an eligible adult relative who is dependent due to a physical or mental infirmity, including an infirm spouse or common‑law partner.

The structure of the new credit is based on Alberta’s current caregiver‑related credits and is intended to align more closely with the federal Canada Caregiver Credit. Under the current framework for 2026, the underlying maximum caregiver‑related amount is $13,180, and the credit begins to be reduced when the dependant’s income exceeds $20,956. Both the credit base and the income thresholds will continue to be adjusted annually in accordance with Alberta’s indexation (escalator) policy starting in 2027.

The new credit will not be available for non‑infirm senior parents or grandparents who reside with the individual.

Vehicle Rental Tax Effective 2027

The budget introduces a new 6% tax on passenger vehicle rentals, effective January 1, 2027.

This tax applies to vehicles designed primarily to transport eight or fewer passengers. It will be calculated on the rental price, excluding federal GST. Itemized charges for insurance and fuel will also be excluded from the tax base.

Further legislative details are expected to be released later in 2026.

Tourism Levy Increase

The tourism levy rate will increase from 4% to 6% effective April 1, 2026.

The tourism levy applies to short‑term accommodation, including hotels, motels, and similar lodging providers. The levy is charged on the price of accommodation.

Education Property Tax Rate Increase

The 2026–27 budget increases education property tax rates as follows:

  • Residential and farmland properties will increase to $2.84 per $1,000 of equalized assessment (up from $2.72).

  • Non‑residential properties will increase to $4.17 per $1,000 of equalized assessment (up from $4.00).

These changes apply to the education portion of property tax collected through municipal property tax bills.

Data Centre Levy Clarification

The budget confirms amendments related to the data centre levy framework introduced in 2025.

The levy will apply at a rate of up to 2% of the value of computing equipment in large, grid‑connected data centres and co‑location facilities. A corresponding non‑refundable tax credit will be available to offset the levy against Alberta corporate income tax so that, once profitable, affected businesses can use the credit to reduce their net provincial corporate tax.

The government also intends to clarify that:

  • The levy will effectively be calculated based on actual power consumption.

  • Power not drawn from Alberta’s existing power grid will be eligible for a 0% levy rate.

Deficit Projections

The government projects:

  • A $4.1 billion deficit for 2025–26.

  • A $9.4 billion deficit for 2026–27.

  • A $7.6 billion deficit for 2027–28.

The budget documents state that no new income taxes or income tax rate increases are being introduced as part of this fiscal plan.

Summary of Key Measures

For families:

  • No change to personal income tax rates or the basic personal amount.

  • New Alberta Caregiver Credit beginning in 2027, replacing existing caregiver‑related credits.

  • Tourism levy increasing to 6% on short‑term accommodation.

  • Higher education property tax rates on residential properties.

For business owners:

  • No change to corporate tax rates.

  • Small business rate remains 2% on the first $500,000 of active business income.

  • Education property tax increase on non‑residential properties.

  • New 6% vehicle rental tax starting in 2027.

  • Clarification of data centre levy rules and corresponding corporate income tax credit.

The 2026 Alberta budget maintains existing income tax rates while introducing targeted changes to levies, property taxes, and tax credits.

If you would like to review how these updates affect your household or business situation, please don’t hesitate eto reach out.

Sources:

Alberta Budget 2026.” Government of Alberta, https://www.alberta.ca/budget.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.